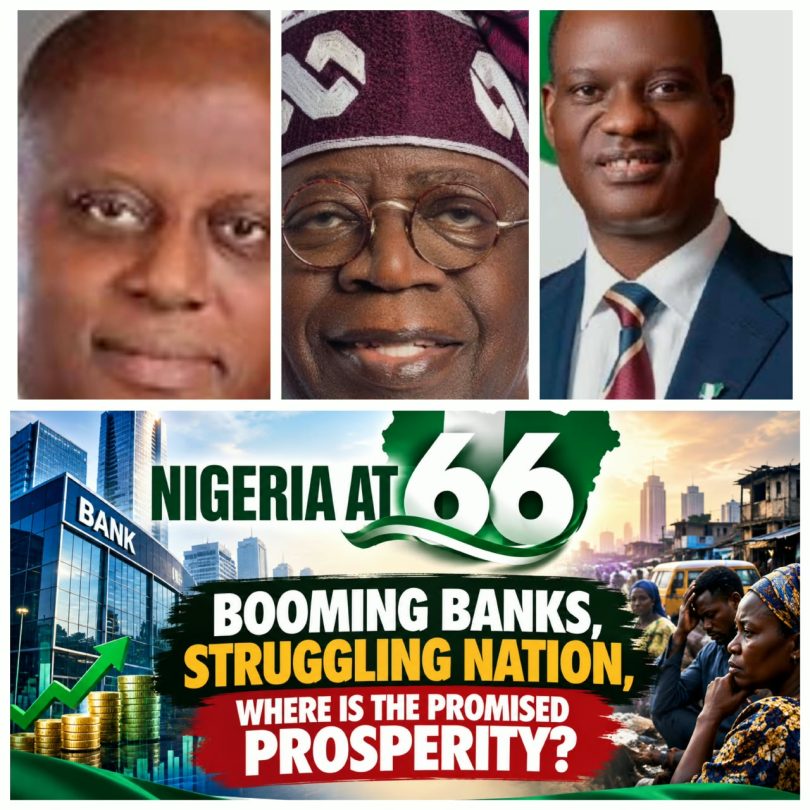
Nigeria @66: Booming Banks, Struggling Nation, Where Is the Promised Prosperity?
By BLAISE UDUNZE
As Nigeria celebrates 66 years of independence, it must ask whether the country has delivered the prosperity and opportunities its people were promised. Beyond the official celebrations, political speeches and repeated claims of national achievement, Nigerians must confront a more important question about the country’s actual progress. Is Nigeria becoming an economy in which its people can increasingly determine their own economic future, or are we merely becoming better at managing the symptoms of longstanding structural weaknesses?
The banking industry provides a useful lens through which to assess whether Nigeria’s economic progress is translating into meaningful benefits for its citizens. Yes, it may not be out of place to argue that banks are not the entire economy, but they occupy a strategic position within it. They mobilise savings, allocate credit, facilitate payments, finance trade, support investment and transmit monetary policy to businesses and households. Their performance can therefore illuminate the strengths and weaknesses of the wider economy.
Nigeria’s banks are raising capital, reporting substantial earnings and operating within a financial system undergoing significant regulatory and structural changes. Meanwhile, beyond the banking halls and financial statements, millions of Nigerians continue to confront the pressures of food prices, transport costs, housing, healthcare, education, unemployment and the struggle to sustain small businesses.
The contrast demands scrutiny. If the financial system is expanding, what is happening to the productive economy? If banks are becoming stronger, are businesses becoming more capable of creating jobs? If national output is growing, are household incomes and living standards improving at a comparable pace? And if reforms are restoring macroeconomic stability, how quickly are their benefits reaching ordinary citizens?
These are not questioning that can be answered by banking results alone. But the banking industry provides an important starting point for assessing whether Nigeria’s economic growth is translating into economic independence and shared prosperity.
The recapitalisation exercise is a major turning point for Nigeria’s banking industry because it could reshape the strength, structure and future direction of banks. Nigerian banks raised about $3.4 billion in new equity, with 33 of 37 banks meeting the revised capital requirements by the March 2026 deadline. The exercise is designed to strengthen financial institutions, improve their capacity to absorb economic shocks and enhance their ability to finance productive activities across the economy, according to the Central Bank of Nigeria.
No doubt, the scale of capital raised is significant and this is because stronger capital buffers can help banks absorb losses, withstand shocks, support larger transactions and maintain confidence in the financial system. The truth is that in an economy exposed to exchange-rate volatility, inflationary pressures and changing global financial conditions, the importance of a resilient banking sector cannot be overstated.
But it is necessary to understand that recapitalisation is a means, not an economic destination. Its ultimate value will depend on what the stronger institutions help the country achieve. A bank can meet its capital requirement, improve its balance sheet and report higher earnings without necessarily transforming the productive capacity of the economy around it.
That distinction is central to Nigeria’s economic independence. Political independence established the country’s sovereignty, but economic independence requires the capacity to mobilise domestic resources, finance development, produce competitively, create opportunities and withstand external shocks. From all indications, it requires an economy in which citizens and businesses have the tools to participate meaningfully in wealth creation rather than remain spectators to growth that has continued to serve only a few individuals.
A country that depends heavily on imported essentials, external financing, foreign technology and volatile commodity receipts remains exposed to developments beyond its control. Strong banks can help reduce that vulnerability by financing domestic production, expanding access to capital and supporting enterprises that create value locally. The challenge here is that they cannot do so effectively in isolation from the wider policy and infrastructure environment.
Nigeria’s economic growth figures also invite a broader assessment. This brings to fore the figure obtained from the National Bureau of Statistics, which reported that real GDP grew by 3.89 percent year-on-year in the first quarter of 2026, compared with 3.13 percent in the corresponding quarter of 2025. Manufacturing grew by 3.29 percent, while trade expanded by 2.08 percent.
Definitely, it would be said that these figures point to an expanding economy. However, the quality of growth matters as much as its rate. Unarguably, growth should be assessed by the productive capacity it creates, the jobs it supports, the incomes it generates, the sectors it strengthens and the extent to which its benefits reach households across different income groups and regions, across the board.
The truth is that an economy can grow without becoming sufficiently productive. It can expand while employment opportunities remain inadequate, while businesses struggle with high operating costs, and while households experience declining purchasing power. Unbeknownst, growth can also be concentrated in sectors that generate substantial output or financial returns but have limited direct effects on employment and household welfare.
Clearly, this is why the distinction between growth and prosperity must remain central to the national conversation. Growth describes an increase in economic activity, while from all indications, prosperity is expected to be reflected in the ability of people to live with security, opportunity and dignity. It includes access to meaningful work, reliable services, affordable essentials, productive assets and the capacity to plan beyond immediate survival.
The banking industry reveals the challenge of connecting the two. Banks are expected to intermediate between savings and investment, directing funds towards businesses and individuals capable of using capital productively. Yet the IMF’s 2026 assessment found that, despite private-sector credit growing by about 20 percent in 2025 after adjusting for exchange-rate valuation effects, credit remained equivalent to only 12 per cent of GDP. The Fund also noted that domestic savings were not being sufficiently channeled into productive investment and that lending remained concentrated in a few sectors.
That finding raises an important question about the role of financial deepening in Nigeria’s development. And this is a clear, stark contradiction because a banking system may be profitable and well capitalised, but if credit remains inaccessible to a broad range of productive enterprises, its contribution to economic transformation will be constrained.
In many situations that have played out in the past, consider the manufacturer seeking financing to purchase machinery, the farmer requiring working capital before harvest, the food processor trying to expand capacity, the technology entrepreneur developing a locally relevant solution, or the small business owner hoping to employ additional workers. Each represents a potential source of production, income and employment. Each also faces the practical question of whether financing is available at a cost and on terms the business can sustain.
When viable enterprises cannot obtain suitable financing, investment is delayed, expansion is limited and employment opportunities are lost. The consequence is not simply a missed lending opportunity for a bank. Beyond what is mentioned, it becomes a clear case of a missed opportunity for the economy to increase output, deepen local supply chains and broaden the sources of household income.