The Federal Government has opened a fresh phase of Nigeria’s tax reform programme, giving a newly inaugurated technical subcommittee six weeks to examine problems emerging from the implementation of the 2025 tax laws and recommend changes for the proposed Finance Bill 2027.
The review will scrutinise issues ranging from Value Added Tax thresholds, withholding tax and capital gains treatment to multiple taxation, taxpayer rights, refunds, small-business safeguards, digitalisation and taxation of the digital economy, following 134 submissions received from stakeholders across the country.
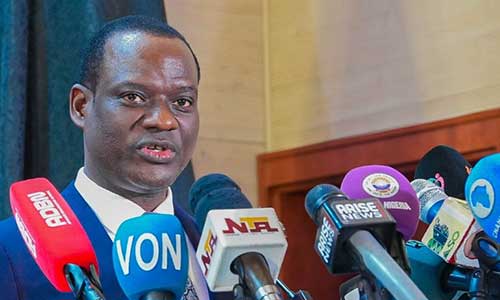
The Technical Subcommittee on Fiscal Policy and Tax Reforms was inaugurated in Abuja by the Minister of Finance and Coordinating Minister of the Economy and Chairman of the Presidential Fiscal Policy and Tax Reforms Committee, Taiwo Oyedele. The government says the exercise is not intended to dismantle or rewrite the major tax reforms enacted in 2025, but to refine them in light of practical problems that have emerged since implementation began.
The laws being reviewed are the Nigeria Tax Act 2025, Nigeria Tax Administration Act 2025, Nigeria Revenue Service (Establishment) Act 2025 and Joint Revenue Board (Establishment) Act 2025, all of which came into full effect on January 1, 2026.
Oyedele said the commencement of implementation had moved the reforms from theory into the real economy, where businesses, taxpayers, administrators and investors were now encountering provisions requiring clarification or adjustment.
“Good reform is a process, not an event. The real test begins when the law meets the economy, as businesses interpret it, administrators implement it, investors respond to it, and citizens experience it,” he said.
According to the minister, the proposed Finance Bill 2027 should therefore address ambiguities, unintended consequences and compliance difficulties exposed by implementation, while seeking to improve Nigeria’s competitiveness and investment environment.
He stressed that the exercise should not be regarded as a reversal of the 2025 reforms.
“The Finance Bill 2027 should not be seen as just another annual legislative exercise. Our task is not to rewrite the 2025 reforms, but to preserve their fundamental principles while learning from implementation and responding to new economic realities,” Oyedele said.
The government’s public Call for Inputs produced 134 submissions from the six geopolitical zones, covering not only taxation but also fiscal policy and management, public financial management, debt, transparency, capital markets and cross-border capital flows.
Among the issues already emerging from those submissions are requests for clearer and simpler provisions governing VAT thresholds, withholding tax and capital gains, as well as stronger measures against multiple taxation and better coordination among federal, state and other revenue authorities.
Stakeholders also called for greater use of digital technology and information-sharing among government institutions so that taxpayers are not repeatedly required to submit information already available to another government agency.
Other proposals seek stronger taxpayer protections, faster tax refunds and safeguards for small businesses. Submissions have also called for tax and fiscal policies capable of encouraging investment and competitiveness in sectors including mining, renewable energy, healthcare and the capital markets.
He said proposed changes should not be assessed simply on whether they are popular, but by identifying the specific problem each proposal seeks to address, its likely cost, who would benefit, who would bear the burden and what unintended consequences could result.
He said proposed changes should not be assessed simply on whether they are popular, but by identifying the specific problem each proposal seeks to address, its likely cost, who would benefit, who would bear the burden and what unintended consequences could result.
The government also wants the next phase of the reforms to focus more deliberately on economic competitiveness, productivity, manufacturing expansion, formalisation and investment.
According to Oyedele, the government’s underlying philosophy is that taxation should be directed primarily at wealth and value creation rather than poverty and productive economic activity.
A significant aspect of the assignment concerns withholding tax.
The subcommittee has been directed to review the Deduction of Tax at Source Regulations 2024 in light of the new tax laws and prepare revised Withholding Tax Regulations.
Oyedele stressed that withholding tax is fundamentally an advance-payment and compliance mechanism and should not become another cost imposed on businesses or effectively operate as a tax on their working capital.