Aliyu Balqees lost trust in digital payments on a Tuesday morning in October 2025, a day the 34-year-old shoe trader says remains etched in her memory. From her modest shop in Ilorin’s Gegele Market, Kwara State, she watched the usual rush of the morning crowd. Like many traders, Balqees had adapted to digital payments following Nigeria’s 2023 cashless policy.
“A customer walked in while I was arranging my wares and asked for corper-style Kito shoes,” Balqees recalled. “They cost ₦3,500 each, and he wanted three pairs, two size 43s for himself and a size 40 for his girlfriend.”
After brief bargaining, they settled on ₦9,000. “He asked for my bank details, and I gave him my GTBank account number,” she said.
“Normally, GTBank alerts take time, so I usually ask customers to show me the transfer receipt,” she noted.
The customer presented a receipt confirming a successful ₦9,000 transfer. Satisfied, Balqees handed over the packed shoes and watched him vanish into the crowded market. Hours passed, but the money never arrived.
The loss ruined her day, but it taught her a hard lesson. “Now, if you don’t have cash, I won’t sell to you,” she said.
Her resolve reflects a growing trend. Across major Nigerian markets, recurring digital payment fraud and network failures are driving traders back to cash, undermining the government’s push for a cashless economy.
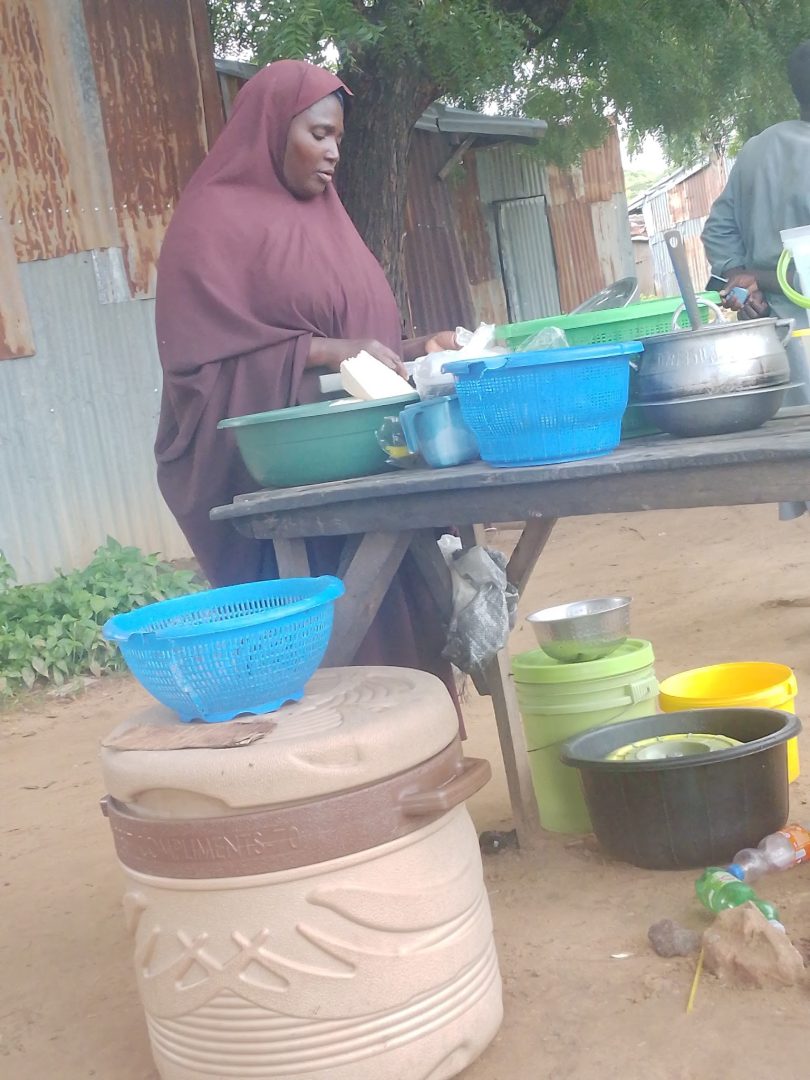
“Cash transactions remain the safest,” said Rahannah Musa, who sells *Dankali da Awara* (fried potatoes and tofu) in Sokoto State’s Wamako Local Government Area. “Customers often claim they sent money, but the transfer never reflects.”
Musa adopted transfer payments in 2023, which initially boosted her sales compared to cash-only vendors. However, network instability frequently forced her to rely solely on transfer receipts.
“That is where the problem lies,” Musa lamented. “When the network fails and the money isn’t credited, you have no recourse, the customer is already long gone.”
Across Nigeria, delayed or missing bank notifications create significant friction for consumers and business owners alike. Most customers rely on SMS or email alerts to verify transactions, but technical glitches, network downtime, and systemic banking failures frequently stall or prevent these deliveries. The resulting uncertainty often triggers transaction disputes, double payments, and immediate distrust.
The crisis worsened in January 2025 when the Nigerian Communications Commission (NCC) authorized telecom operators to disconnect Unstructured Supplementary Service Data (USSD) access for nine banks over a ₦200 billion accumulated debt. The suspension left millions of customers unable to conduct USSD banking or receive transaction alerts, compounding the notification bottleneck.
According to a 2025 survey carried out by journalists, 71 per cent of respondents preferred cash over digital payments. 19 per cent use digital payments occasionally but still have concerns, whereas 10 per cent say they operate fully cashless transactions.
Of the 330 traders who attempted the survey, 52% reported falling victim to fake transactions at least once. 27% lost money to fraudulent digital transactions, and 15% stopped accepting bank transfers due to multiple bad incidents.
The Story Of Salamatu Who Loses 8,000 naira Daily to Fake Transfer
Salamatu Bala, another vendor in Sokoto, is among those who have fallen victim to fake transfers. Yet, she feels she has no choice but to continue accepting digital payments to stay in business.
The Kunu da Kosai (pap and fried bean cake) seller reflected on how deceitful some customers can be.
“Sometimes, after a grueling day, you check your balance and realize you are short by ₦7,000 or ₦8,000,” Salamatu explained.
“How much profit do I even make from this business for ₦7,000 to just vanish like that?” she asked.
She recalled a day a customer walked away without paying for ₦1,100 worth of kunu. “I even helped him by asking another customer to transfer ₦500 to his account so he could send me the full ₦1,600 via OPay,” she said. “He claimed his network was poor and promised to withdraw cash nearby and return. I never saw him again.”
She added that such incidents, compounded by her difficulty navigating digital banking apps, lead to routine financial losses. “That is why I always prefer customers who pay with cash,” she said.
The Cost of Digitalisation
Nigeria’s digital payment ecosystem has expanded dramatically since the introduction of the 2023 cashless policy. Data from the Nigeria Inter-Bank Settlement System (NIBSS) shows that instant digital payments surged to ₦1.07 quadrillion in 2024, up from ₦600.36 trillion in 2023. During the same period, Nigerians executed 1.38 billion Point-of-Sale (POS) transactions valued at ₦18.32 trillion. While these digital innovations aim to boost transaction efficiency, lower cash-handling risks, and deepen financial inclusion, a primary goal outlined by the Central Bank of Nigeria (CBN)—they have also created new vulnerabilities.
Yet, behind these record figures lies a darker reality: a growing shadow economy where scammers systematically target small-scale traders like Balqees, Rahannah, and Salamatu.
According to the CBN’s Nigeria Payments System Vision 2028 report, banks and their customers lost ₦134.48 billion to financial fraud between 2020 and 2025. Total attempted fraud during that period reached ₦187.79 billion, underscoring the massive scale of cybercrime tracking the nation’s digital payment expansion.
These losses cut across multiple payment channels, including ATMs, mobile and internet banking, POS terminals, e-commerce platforms, cheques, and over-the-counter transfers.
The CBN acknowledged that while rapid digital adoption and fintech innovation have streamlined commerce, they have also broadened the attack surface for fraudsters. Although regulators and financial institutions have strengthened joint oversight, the central bank warned that evolving fraud schemes continue to threaten the stability of the country’s digital financial ecosystem.
Nigeria’s Fake Transfer Economy
In June 2025, popular TikToker, ROZAY AI TOOLS & TECH, introduced his over four hundred thousand followers to ‘slipcraft.net’. A website where scammers transfer and generate receipts for non-existent funds from fintech apps in Nigeria, including PalmPay, OPay, Kuda amongst others.
“This website will blow your mind. I just discovered a website that does fake transfers. Stay calm, let me show you how it works so you won’t fall victim.”
Rozay, in the video, took his followers step by step through setting up and using an account. Rozay continuously cautioned his followers not to use the tool wrongly and even warned that the video was for “educational purposes” only. But legal experts like Abdulwasiu Olokooba, a Kwara-based legal practitioner and digital rights advocate, would disagree.
“A disclaimer is not a legal shield from liability. Nigerian courts examine substance, intent, and effect rather than form. If the content provides practical tutorials on navigating a tool whose primary known use is fraud (creating fictitious balances, generating receipts that can be used to deceive), the creator risks liability for aiding and abetting, conspiracy, or facilitating computer-related fraud under the Cybercrimes Act,” Abdulwasiu told our reporter.
He further said that disclaimers such as “allegedly” or “educational purposes only” do not automatically negate guilty mind or public-policy considerations.
“Where the surrounding context (circulation among known fraud communities, sales of access points, and demonstrated use in real scams) shows the material is intended or likely to enable crime, criminal responsibility attaches. Civil or regulatory consequences for platforms and creators can also arise. True educational content on cybersecurity, like how banks detect fake receipts, is protected expression; instructional material that equips scammers is not,” he clarified.
But Rozay is not the only user guilty of this. Similar messages were passed in other videos, as seen here and here.
Abdulwasiu added that the fact that the videos remain accessible and circulating is a breach of TikTok’s Community Guidelines, which explicitly prohibit content that promotes or facilitates scams, fraud, or deceptive schemes. The platform states it uses proactive technology, human reviewers, and user reports, and claims high removal rates (often before user reports) for fraud-related material.
“When tutorial-style content tagged “educational” nevertheless reaches audiences and enables real-world fraud, it demonstrates gaps in detection, particularly of coded or disclaimer-shielded instructional material. Volume, algorithmic amplification, and the challenge of distinguishing genuine education from facilitation contribute to enforcement shortfalls. Platforms are not expected to be perfect, but persistent public availability of clearly facilitative content indicates a failure to meet their own stated standards.”
How Does Slip Craft Work?
Following the video’s explanation, this reporter searched slipCraft.net online as instructed by Rozay. The website’s main page welcomes customers with a strong but compelling message: “Generate receipts, send flash emails, build support pages, and build login pages, all from one powerful dashboard.” According to Rozay, below that is a ‘Get Started for Free’ icon that new users can click to get started. This reporter, following the instructions, using a burner email, created an account.
After signing up the website’s inner dashboard revealed a more disturbing fact: beyond Fintech’s fake transfer and receipt generation, the website can send flash emails for cryptocurrency wallets, including Binance, Bybit, Coinbase, PayPal, and more. It was at that point that the phrase from the homepage made sense. The tool was meant for fraudulent activities. But this investigation is an enquiry into the fake transfer economy.
Records obtained from WHOIS, a public database of domain registration information, show that the domain name slipcraft.net is registered with Cloudflare, Inc, a Canada-based registrar headquartered in British Columbia. A calculated move, as scammers often pick jurisdictions far from their targets so as to avoid takedowns.
The records reveal that the domain was only registered on May 13, 2025, just a month before Rozay’s video. It was updated on April 23, 2026 and set to expire in May 2027.
ICANN LOOKUP, another open source tool for website analysis, corroborated this reporter’s findings on WHOIS domain by naming Cloudflare Inc as the registrar. Meanwhile, the perpetrators names and contact information declared “DATA REDACTED”.
“It means the website owner hides their identity,” noted Nurudeen Akewushola, a senior journalist with the International Center for Investigative Reporting (ICIR).
Mr Akewushola, who had also investigated fraudulent websites using Artificial intelligence to lure Nigerians into ponzi schemes, explained that although legitimate businesses do that too, shady websites use that to hide.
Back on the dashboard, when I clicked the OPay icon, it took me to an interface that looked exactly like the real account. The balance on my fake account was #150,000, an amount I don’t know how it got there.
I was more shocked when I checked my (fake) Kuda account and found the same amount.
To test whether it works like the real OPay, I decided to make a transfer to my real OPay account. I clicked ‘to OPay’ and inserted my real account number. Surprisingly, it brought up my real name as used on my real account.
When I tried to transfer #10,000 to my real OPay account, the website said, “You need to have at least 475 points to complete this transaction.”
“Click here to buy more points,” read the instruction that followed.
This reporter followed the instruction by tapping on the ‘Click here to buy more points’. The website linked me up with another user willing to sell points. And the price for points differs. At the rate of #1.05 per point, you can choose to buy points worth a minimum of #1,500 and #100,000 maximum. I opted for the minimum and sent #1,500 to one Joseph Nnamani, with 5238010219 being the Moniepoint account provided.
After the transfer was completed, I went back to click on ‘I have sent the money’. The website directed me to the vendor’s dm on WhatsApp, where I would later share the receipt of the transaction
Moments after sharing the receipt as instructed, the vendor acknowledged the money. I checked the website and realised the transaction had gone through successfully. My dashboard reflected 1,428.57 points. Way more than what I needed to transfer.
I transferred #10,000 from the parody account into my real OPay account with 475 points and even generated a receipt that looks exactly like the original one for the fake transaction. For the receipt generation, I was charged 650 points.
The transaction receipt looked genuine. Even though I didn’t receive any money in my real account, it thus becomes difficult for anyone to spot any difference between Slipcraft and genuine receipts.
“In a place like Nigeria where bank alerts take time, and most traders do not know how to navigate bank apps, most traders are already vulnerable. Except for those who have a point of sale (POS) machine,” said Aminu Kure, a banker from Sokoto.
“But how many of these petty traders can afford such?” he queried.
In Nigeria, users of Slipcraft risk conviction for the following crimes under the Cybercrimes Act 2015 (as amended 2024):
Section 13 criminalises computer-related forgery (knowingly accessing a system and inputting, altering, deleting or suppressing data to produce inauthentic data intended to be treated as authentic). Penalty includes imprisonment for not less than 3 years or a fine of not less than ₦7,000,000 or both.
Also Section 14 talks about computer-related fraud. Penalties start at not less than 3 years or ₦7 million and rise to not less than 5 years or ₦10 million for the electronic-message variant.
Related provisions cover identity theft/impersonation (Section 22), fraudulent issuance of electronic instructions, and misuse of devices. Attempt, conspiracy, and aiding and abetting are also punishable (Section 27).
“Advance Fee Fraud and Other Fraud Related Offences Act 2006: Obtaining property by false pretence (or inducing delivery of property) with intent to defraud carries imprisonment of not less than 7 years and up to 20 years, without option of fine in many cases,” said Abdulwasiu.
He further said that the Criminal Code Act, Penal Code and the EFCC (Establishment) Act cover obtaining by false pretences (the classic “419” offence) and empower the Economic and Financial Crimes Commission to investigate, prosecute, freeze accounts, and seek forfeiture of proceeds.
“Operators of the “backdoor” website, users who create parody accounts and generate receipts to induce real transfers or goods/services, and those who facilitate (including by selling “points”) face arrest, prosecution in the Federal High Court or specialised offences courts, imprisonment, fines, and asset forfeiture. Recent EFCC cases involving unauthorised credits, system manipulation, and fake documentation illustrate that courts treat electronic forgery and fraud seriously, often ordering restitution and concurrent sentences. Money-laundering provisions can apply to the proceeds. Jurisdiction extends to acts affecting Nigerian systems or victims even if servers are offshore,” he ended.
Beyond TikTok
A review of the website revealed there is a link leading to a Telegram community with over 61,000 subscribers. The activities in the community cut across instructions on how to navigate the website, how many points it costs for receipt generation and updates about new features on the website.
A message from the group dropped in June 2026 reads:
“Our OPay prank service just got better. At this point, it is almost impossible to tell whether you are using the real OPay app or our OPay prank service.”
“We made a small update to the Opay Prank Service.
You can now change a transaction status from successful to reversed transaction,” another message from August read.
Abdulwasiu believes Telegram’s Terms of Service prohibit scams and fraud. “The platform asserts that it removes such content when detected, employs AI for public sections, and has deleted millions of groups/channels,” he explained.
He added that public groups that openly discuss navigation of the website and sell “points” for access fall within the category of content Telegram claims to moderate. Continued operation of such groups shows inadequate proactive or responsive enforcement on the public side of the platform.
“Private chats and channels present different technical and privacy challenges; the failure is clearer for public groups that function as open marketplaces for tools of fraud.”
He advised this investigation to prioritise evidence preservation, liaison with EFCC or Nigeria Police cybercrime units, and formal notices to the platforms under their own reporting mechanisms and applicable Nigerian or foreign laws.
Kuda Confirms Findings
Before publication, I shared my findings with both Kuda and OPay via email.
In response, the Kuda team acknowledged my email and assured me that the fraud team was investigating the matter. In a subsequent response, the fraud team later confirmed this reporter’s findings,
“We explored the website and found elements impersonating the brand,” the feedback reads in part.
Opay is yet to give responses to questions sent to its customer care email as of press time.
On the platform side, this reporter reported the Telegram channel, ‘Slipcraft ’, to Telegram. On TikTok, Rozay’s and two others’ similar videos were reported to TikTok for promoting fraud.
Also, efforts were made to reach the Economic and Financial Crimes Commission (EFCC), through its spokesperson, Mr Dele Oyewale. But all calls placed to his line were left unattended, and messages seeking a response sent to his private dm on WhatsApp were viewed but left unreplied at the time of filing this report.
Slipcraft Responds,
In response to the questions asked by this reporter, Slipcraft directed this reporter to access its terms. “Every question here is answered in our terms,” reads a private message shared with this reporter via Telegram.
In its terms, it is explained that Slipcraft is a creative content tool. It generates simulated emails, receipts, notifications, and visual mock-ups styled after the look and feel of widely recognized payment, wallet, and messaging brands. It is intended for novelty, comedy, design prototyping, UX research, content creation, and security-awareness education.
“Slipcraft is not a bank, payment processor, money-transmitter, escrow service, or messaging service of any third-party brand. Slipcraft does not move money, hold funds, settle transactions, or send authentic notifications on behalf of any platform. Any output produced by the Service is simulated content only and has no financial validity whatsoever.”
The terms also noted that Slipcraft may not be used for deceiving, defraud or impersonate. Also, may not be used for money laundering, fabrication of evidence for legal proceeding, phishing, harassment, among others.
“Engaging in any prohibited use will result in immediate termination, forfeiture of any balance or credits, and may be reported to law-enforcement and affected third parties,” it warned.
However, when this reporter asked whether the company is aware that its services are being used for fraud, the handler suddenly stopped responding. Slipcraft is yet to give answers to follow up questions asked as at press time.