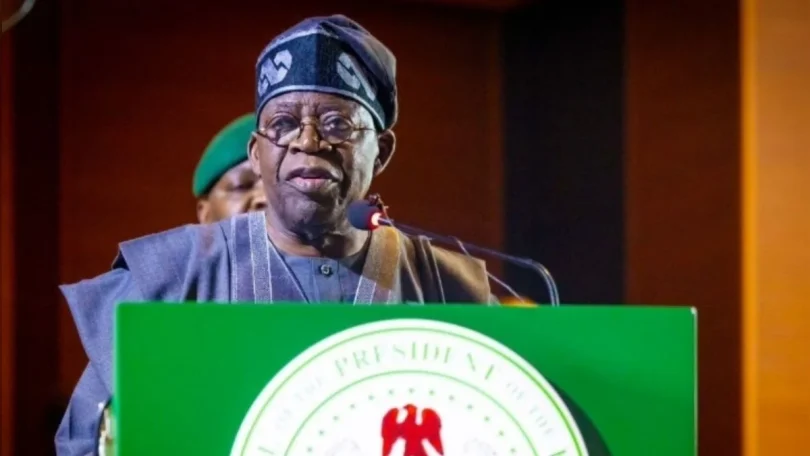
President Bola Tinubu has approached the House of Representatives to seek approval for fresh external borrowing estimated at N10.8 trillion to finance projects captured in the 2026 Appropriations Act.
The request is part of the Federal Government’s plan to secure additional foreign financing for infrastructure development and other key sectors of the economy.
Tinubu said the proposed borrowing would support the implementation of budgeted projects and help sustain the economic gains recorded under his administration.
The President communicated his request to the lawmakers in a letter, seeking their approval for the implementation of the external borrowing plan contained in the 2026 budget.
Tinubu’s administration has faced criticism from labour organisations and other Nigerians who question the need for additional borrowing, particularly following the removal of the petrol subsidy and the government’s claims of improved revenue generation.
However, Tinubu has maintained that borrowing is necessary to address Nigeria’s infrastructure deficit and create the foundation for sustainable economic growth.
The President recently defended his administration’s borrowing strategy, insisting that the country’s economic ambitions would remain difficult to achieve without substantial investments in transportation, electricity, healthcare, education and other critical sectors.
In a statement titled From Reforms to Delivery: Our Infrastructure Investment and Growth Strategy, Tinubu argued that the debate surrounding foreign loans should focus on the benefits and long-term value of the projects being financed rather than the amount borrowed.
“The key question is not how much we borrow, but what we build, the value we create and the future we leave behind,” he said.
Tinubu identified several major infrastructure projects expected to benefit from the government’s investment programme.
They include the Lagos-Calabar Coastal Highway, Sokoto-Badagry Superhighway, Trans-Sahara Superhighway, improvements to the national electricity grid and the modernisation of major commercial ports in Lagos.
According to the President, the projects are expected to improve transportation, connect important commercial centres and reduce the cost of moving goods across the country.
He explained that investments in infrastructure would also support agricultural production, manufacturing and other businesses by making it easier for farmers and industrial operators to transport their products to different markets.
The administration also plans to direct investments towards healthcare, education and vocational training as part of its broader economic development programme.
Tinubu particularly highlighted the expected economic benefits of the Lagos-Calabar Coastal Highway, saying the project could reduce transportation costs along its route by between 15 and 20 per cent.
He further projected that the highway could contribute as much as two per cent to Nigeria’s Gross Domestic Product through increased commercial activities, tourism and industrial development.
The President said the project was also expected to generate employment opportunities for Nigerians, with approximately 100,000 direct jobs anticipated in construction and engineering. More than 150,000 indirect jobs could also emerge in logistics, building materials and related sectors.
“We are building more than highways. We are opening economic corridors, connecting markets, supporting industries and reshaping Nigeria’s economic geography,” he said.
Tinubu maintained that Nigeria must significantly improve its infrastructure if it hopes to achieve its ambition of becoming a $1 trillion economy by 2030.
“We cannot build a $1 trillion economy with infrastructure designed for an economy a fraction of that size,” he added.
The President also defended the borrowing plan by pointing to improvements in some economic indicators since his administration introduced major reforms in May 2023.
He identified the removal of petrol subsidy, unification of the foreign exchange market, tax reforms and measures aimed at controlling inflation as important steps taken to improve government revenue and strengthen the economy.
According to the figures presented by the President, Nigeria recorded economic growth of 4.43 per cent in the second quarter of 2026.
He also disclosed that headline inflation declined to 14.63 per cent in September from 20.98 per cent recorded during the corresponding period of the previous year.
On the country’s external financial position, Tinubu said Nigeria’s gross external reserves stood at $55.1 billion as of October 9, 2026, with net reserves estimated at approximately $46 billion.
He further stated that the country’s tax-to-GDP ratio had increased to 12.5 per cent from seven per cent.
The President also highlighted an increase in allocations from the Federation Account Allocation Committee (FAAC), saying net distributions rose by 44 per cent from N15.2 trillion in 2024 to N21.9 trillion in 2025.
Tinubu argued that these developments had improved Nigeria’s financial standing and strengthened its ability to attract international investments.
He cited assessments by global credit rating agencies, Nigeria’s return to Frontier Market status and the successful issuance of Eurobonds as indications of improving investor confidence.
“These are not political endorsements; they are independent assessments by global rating agencies, index providers, regulators and investors, recognising stronger external reserves, improved macroeconomic management and greater financial credibility,” he said.
The President also explained that his administration was considering longer-term borrowing arrangements to ensure that repayment periods correspond with the useful lifespan of the infrastructure projects being financed.
He said such an approach would reduce the pressure associated with frequent debt repayments and allow the government to negotiate more favourable borrowing conditions.
However, Tinubu acknowledged the financial obligations associated with increased borrowing and the need for the government to maintain spending discipline.
He disclosed that Nigeria’s public debt stood at 35.75 per cent of GDP in the second quarter of 2026, while debt servicing consumed approximately 65 per cent of government revenue in the first half of the year.
The President said the Federal Executive Council’s economic plan included measures to prevent the government from relying on money printing to finance budget deficits.
He also said the administration would avoid taking on spending commitments that were not supported by available funds, particularly during the period leading to the next general election.
Despite the government’s explanation, the proposed borrowing programme has continued to attract criticism from organised labour.
The Nigeria Labour Congress (NLC) has questioned why the Federal Government needs additional foreign loans despite repeatedly claiming that its revenue has improved following the removal of the petrol subsidy.
NLC President, Joe Ajaero, raised the concerns during an appearance on Channels Television’s The Morning Brief, where he challenged the government to explain the continued need for borrowing from international financial institutions.
Ajaero specifically questioned the justification for approaching institutions such as the International Monetary Fund and the World Bank for additional financing when the government had maintained that subsidy removal had increased available revenue.
“If you come out to tell us that subsidy is gone, that you are making more money and then you are giving more money to states, what is the justification for continually borrowing from the International Monetary Fund and the World Bank and other agencies when there is enough money?” he asked.
The labour leader also drew attention to the increase in international crude oil prices, arguing that the development should be considered when assessing the country’s borrowing requirements.
He noted that the 2026 budget was prepared using an oil price benchmark of $70 per barrel.
However, crude oil prices had risen above $100 per barrel following tensions involving the United States and Iran.
Ajaero questioned whether the government should continue seeking foreign loans under the circumstances, particularly if higher oil prices translate into increased revenue for the country.
“If the 2026 budget was prepared with crude oil price benchmarked at $70 per barrel and now sells above $100 per barrel due to the US-Iran crisis, should this country still be taking loans?” he asked.
He further argued that the Federal Government needed to explain how the additional borrowing would affect the country’s debt obligations, especially considering the increased revenue available to the government and allocations to oil-producing states.
Ajaero, however, clarified that the NLC does not have the constitutional responsibility to approve or reject government borrowing.
He acknowledged that such decisions rest with the appropriate government institutions but maintained that Nigerians and relevant authorities must demand transparency and accountability.
The latest disagreement places the proposed N10.8 trillion borrowing request at the centre of an ongoing debate over the Federal Government’s economic priorities, debt management strategy and infrastructure financing plans.
While the Tinubu administration maintains that long-term borrowing is necessary to address the country’s infrastructure challenges and stimulate economic activities, organised labour wants the government to explain why increased revenue has not reduced its dependence on external financing.
Tinubu, on his part, said the government would ultimately be judged by what it delivers with the funds secured through borrowing.
“Securing financing is only the beginning. The real achievement lies in completing projects, delivering value for money, and improving Nigerians’ lives,” he said.