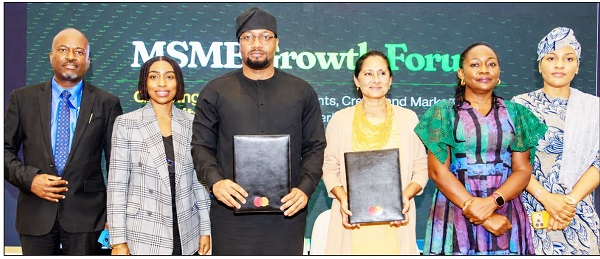
Nigerian small business owners may soon have access to more digital business tools, practical training and support to improve their operations following a new partnership between global payments technology company Mastercard and the Small and Medium Enterprises Development Agency of Nigeria (SMEDAN).
The two organisations have signed a Memorandum of Understanding (MoU) to explore initiatives aimed at helping micro, small and medium-sized enterprises (MSMEs) adopt digital technology, improve business efficiency and participate more actively in Nigeria’s formal economy.
The announcement, made on 12 November 2026, followed the SMEDAN MSME Growth Forum in Lagos, which brought together business owners, financial institutions, policymakers and other stakeholders to discuss the challenges facing Nigerian entrepreneurs.
For small business owners struggling with digital payments, access to customers, business management and financing, the partnership could create new opportunities.
However, there is an important point entrepreneurs should understand: the agreement does not currently announce a cash grant, business loan or dedicated application portal. Instead, it establishes a framework through which Mastercard and SMEDAN will explore practical initiatives to support Nigerian businesses.
Here is what the partnership means, the areas it is expected to address and what Nigerian entrepreneurs should watch out for.
What Is the Mastercard and SMEDAN Partnership About?
The partnership is designed to help Nigerian MSMEs embrace digital technology and strengthen their ability to compete in an increasingly digital economy.
Through the MoU, Mastercard and SMEDAN intend to explore opportunities to support businesses in areas including:
- Digital payments and financial technology.
- Digital skills and business training.
- Improved operational efficiency.
- Digital marketing and customer acquisition.
- Access to markets and business networks.
- Business formalisation and participation in the formal economy.
- Connections to financial institutions and other business support organisations.
The collaboration builds on the Federal Ministry of Industry, Trade and Investment’s support for the design and piloting of a national MSME Digitisation Programme.
The broader objective is to help small businesses move beyond traditional ways of operating and adopt tools that can improve productivity, customer service and business growth.
SMEDAN Director-General, Charles Odii, said Nigerian entrepreneurs need more than encouragement to adopt digital technology. They need practical tools, skills and support that reflect the realities of running a small business.
Mastercard’s Executive Vice-President for Growth Segments, Tara Nathan, also highlighted the challenges small businesses face in accessing digital capabilities, skills development and finance.
What Will Nigerian Small Businesses Gain from the Partnership?
Although the specific programmes to be delivered under the MoU have not yet been announced, the organisations have identified several areas where their collaboration could support entrepreneurs.
Here are five areas Nigerian business owners should watch.
1. Access to Digital Payment Solutions
One of the biggest opportunities is helping small businesses improve how they receive and manage payments.
Many Nigerian businesses still rely heavily on cash transactions, informal transfers and manual payment records.
Adopting digital payment solutions can help businesses:
- Receive payments more conveniently.
- Reduce the risks associated with handling cash.
- Keep better transaction records.
- Monitor daily sales and business performance.
- Improve customer convenience.
- Build a more reliable financial history.
For example, a small supermarket that records all its sales digitally can have a clearer picture of daily revenue, inventory movement and customer purchasing patterns.
These records can also become useful when approaching financial institutions for business financing.
2. Digital Skills and Business Training
The partnership also aims to address the digital skills gap affecting many Nigerian MSMEs.
Small business owners increasingly need more than basic knowledge of social media to compete.
They need to understand how to use digital tools to manage their businesses, attract customers and improve productivity.
Areas of potential support include:
- Digital marketing.
- Online customer acquisition.
- Social media business strategies.
- Digital payment management.
- Business technology adoption.
- Staff digital skills development.
The SMEDAN MSME Growth Forum already included practical masterclasses on digital marketing and other business capabilities.
These sessions focused on helping entrepreneurs attract and retain customers online and improve productivity across different sectors, including agriculture.
3. Improved Access to Markets
Digital technology can help small businesses reach customers beyond their immediate neighbourhoods.
A fashion designer operating in Lagos, for example, can use digital platforms to sell to customers in Abuja, Port Harcourt, Accra or other markets.
Similarly, a food processing business can use digital tools to connect with distributors, retailers and institutional buyers.
By exploring collaborations around digital capabilities and business connections, Mastercard and SMEDAN hope to create better opportunities for Nigerian entrepreneurs to participate in wider markets.
4. Better Business Operations and Efficiency
Many small businesses struggle not because they lack customers, but because their internal processes are inefficient.
Manual bookkeeping, poor inventory management, weak customer records and inadequate financial planning can limit growth.
Digital tools can help entrepreneurs improve:
- Stock and inventory management.
- Accounting and bookkeeping.
- Sales monitoring.
- Customer relationship management.
- Business reporting.
- Employee productivity.
- Financial planning.
For a growing business, these improvements can make the difference between simply generating sales and building a sustainable enterprise.
5. Better Preparation for Access to Finance
Access to finance remains one of the biggest challenges facing Nigerian MSMEs.
However, lenders often need more than a business owner’s request for money before approving financing.
They want evidence of business activity, revenue, cash flow, repayment capacity and financial discipline.
Digital payment records and properly maintained business accounts can help entrepreneurs demonstrate their financial performance.
This is particularly important for businesses that operate informally or have limited financial documentation.
While the Mastercard-SMEDAN agreement has not announced a new loan facility, improved financial records and business capabilities could help participating businesses become better prepared to approach financial institutions.
Which Businesses Could Benefit?
The proposed collaboration is intended to support Nigerian micro, small and medium-sized businesses across different sectors.
Potential beneficiaries could include:
Retail and trading businesses: Small shops, supermarkets, fashion retailers and distributors that want to improve payments, inventory management and customer engagement.
Agricultural businesses: Farmers, processors, aggregators and agribusinesses that need digital tools to improve productivity and market access.
Manufacturing businesses: Small manufacturers seeking better production management, sales records and operational efficiency.
Service businesses: Restaurants, logistics companies, professional service providers and other businesses looking to improve customer acquisition and payment processes.
Technology and creative businesses: Entrepreneurs using digital platforms to sell products, deliver services or reach new customers.
The partnership has not published a formal list of eligible business categories, selection criteria or beneficiary targets. These examples illustrate the types of businesses that could benefit from the areas of support being explored.
Is Mastercard or SMEDAN Giving Nigerian Businesses Grants or Loans Under This Partnership?
This is an important question because many Nigerian entrepreneurs are searching for funding opportunities.
As of 16 November 2026, the Mastercard-SMEDAN partnership has not announced a dedicated grant, loan facility, funding amount or application deadline.
The agreement is focused on exploring initiatives that support digital adoption, skills development, business efficiency and growth.
It would therefore be misleading to describe the partnership as a new ₦10 million grant, a business loan scheme or a direct cash support programme.
Entrepreneurs should watch for further announcements from Mastercard and SMEDAN concerning specific programmes that may emerge from the agreement.
How Can Nigerian MSMEs Participate?
Although a dedicated application portal has not been announced, entrepreneurs can begin preparing their businesses to take advantage of future initiatives.
Here are five practical steps:
1. Formalise your business
If your business is not registered, consider completing the appropriate business registration with the Corporate Affairs Commission (CAC).
Formal registration can help improve your access to business support programmes, partnerships and financial services.
2. Start using digital payment solutions
Adopt reliable digital payment channels that allow you to receive and record customer payments.
3. Keep proper business records
Maintain sales records, expense records, inventory information and basic financial statements.
4. Improve your digital skills
Learn how to use digital marketing, online sales platforms, bookkeeping software and other tools that can improve your business.
5. Follow official SMEDAN announcements
Watch for further information on programmes, training opportunities and digital support initiatives arising from the partnership.
You can visit the agency’s official website:
https://smedan.gov.ng/
What Happened at the SMEDAN MSME Growth Forum?
The partnership was announced following the SMEDAN MSME Growth Forum in Lagos, which brought together government officials, financial institutions, entrepreneurs and development partners.
The event examined the challenges facing Nigerian businesses and the solutions required to help them grow.
A key discussion, titled Informal to Inclusive: Payments, Policy and the Path for Nigeria’s Small Businesses, featured Mastercard’s Tara Nathan and Aisha Rimi, Executive Secretary and Chief Executive Officer of the Nigerian Investment Promotion Commission (NIPC).
Another session, titled Beyond Credit: The Solutions Nigerian SMEs Need to Grow and Scale, featured representatives from Access Bank, Wema Bank, AFEX and SMEDAN.
The discussions highlighted the importance of looking beyond loans and grants when supporting small businesses.
Entrepreneurs also participated in practical masterclasses covering digital marketing and solutions to improve productivity and market access.
Frequently Asked Questions About the Mastercard-SMEDAN Partnership
1. What is the Mastercard-SMEDAN partnership about?
Mastercard and SMEDAN have signed an MoU to explore initiatives that will help Nigerian MSMEs adopt digital tools, improve business efficiency and participate more fully in the formal economy.
2. Is Mastercard giving ₦10 million grants to Nigerian businesses?
No. The partnership announcement does not include a ₦10 million grant or any other specific cash grant.
3. Can I apply for the Mastercard-SMEDAN programme?
A dedicated application process or beneficiary registration portal has not been announced. Entrepreneurs should monitor official announcements from SMEDAN and Mastercard.
4. Will the partnership provide free digital training?
Practical masterclasses were held at the SMEDAN MSME Growth Forum. However, a nationwide free training programme, application process and implementation schedule have not yet been announced.
5. Which businesses can benefit?
The partnership is intended to support Nigerian MSMEs. Potential areas of relevance include retail, agriculture, manufacturing, services and technology businesses.
6. Will the partnership help small businesses access loans?
The agreement recognises access to finance as an important growth challenge and explores wider business capabilities and connections. However, no dedicated loan facility has been announced.
7. What is the role of SMEDAN?
SMEDAN is the Federal Government agency responsible for promoting and supporting the development of micro, small and medium-sized enterprises in Nigeria.
8. Where can I get updates about the partnership?
Entrepreneurs can monitor the official websites of SMEDAN and Mastercard:
Final Thoughts: A New Opportunity for Nigerian Small Businesses?
For years, discussions about MSME development in Nigeria have focused heavily on access to funding.
While affordable finance remains important, businesses also need digital capabilities, better management systems, market access and the skills required to compete.
The Mastercard-SMEDAN partnership recognises this wider challenge.
If successfully translated into practical programmes, it could help thousands of Nigerian entrepreneurs improve how they receive payments, manage operations, reach customers and build more sustainable businesses.
For now, however, business owners should understand that the MoU is a framework for future collaboration, not an open grant or loan application.
MSME Africa will continue to monitor the partnership and report any confirmed training programmes, digital support initiatives, funding opportunities or application windows announced for Nigerian businesses.
Entrepreneurs should follow official SMEDAN announcements and watch this space for updates.